

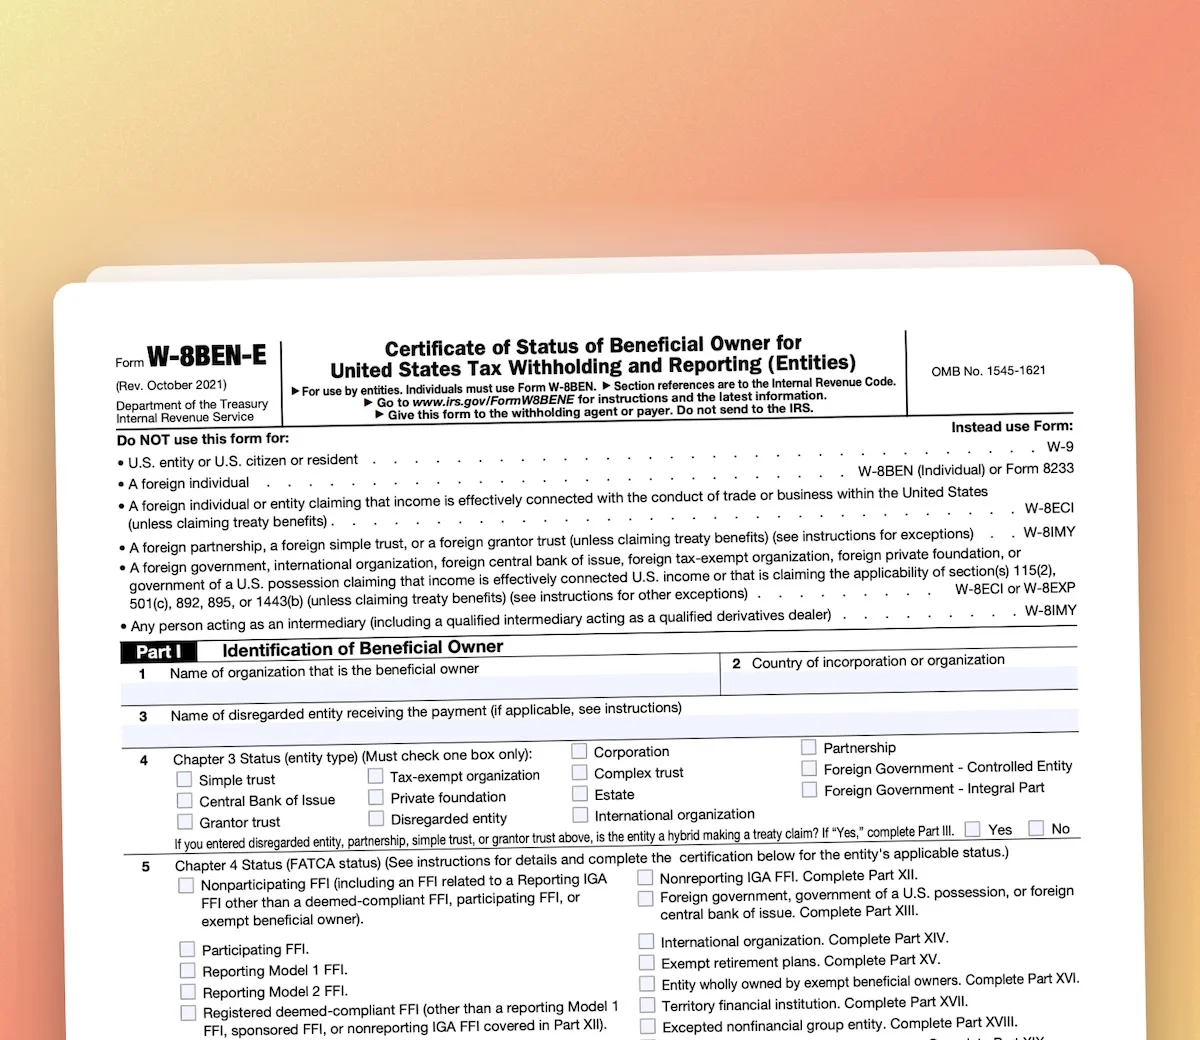
You don’t need to hire a US accountant to fill in a W-8BEN-E form. This guide walks UK businesses through what the form is, who actually needs it, how to fill it in, and the mistakes that most often get it sent back.
What Is a W-8BEN-E, and Why Is Your US Client Asking for It?
Form W-8BEN-E is an IRS document that foreign (non-US) entities use to confirm their foreign status and, where it applies, claim a reduced rate of US withholding tax under a tax treaty.
W-8BEN-E is actually one of three W-8BEN forms. Here’s the basic difference to keep in mind:
- Form W-8BEN is for non-US individuals (like a UK sole trader)
- Form W-8BEN-E is for non-US entities (like a UK limited company)
- Form W-8IMY is for intermediaries or flow through entities (this can be relevant for some LLPs, more on that below)
You’ll usually be asked for this form by:
- US companies paying you directly for services, royalties, or licensing
- Payment platforms (Stripe, PayPal, Upwork, Amazon, and so on) during onboarding
- US banks or brokerages if you hold US connected accounts or investments
Which Form Does Your UK Business Actually Need?
Before you touch the form itself, make sure you’ve got the right one for your business type. This is where most of the confusion starts.
| UK Business Type | Correct Form | Why |
|---|---|---|
| Limited company (Ltd) | W-8BEN-E | You’re a separate legal entity. This is the standard case the form is built for. |
| Sole trader | W-8BEN (not W-8BEN-E) | You’re treated as an individual for US tax purposes, not a separate entity. |
| LLP | Depends, could be W-8BEN-E or W-8IMY | LLPs are entities under UK law, but US tax classification doesn’t always follow UK legal form. If the LLP is acting as a flow through or intermediary rather than the true beneficial owner, W-8IMY may be the right form instead. |
If you run an LLP, don’t just default to W-8BEN-E without checking this first. Get advice on how your LLP is classified for US tax purposes. Getting this wrong is one of the most common reasons US payers reject the paperwork.
How the UK US Tax Treaty Affects Your Withholding Rate
The standard US withholding rate on US source income (dividends, interest, royalties, rents) paid to foreign entities is 30%. The UK US tax treaty brings that rate down, but only if you claim it correctly on the form and meet the underlying conditions. The main one is that you need to be the beneficial owner of the income, not just someone collecting it on another party’s behalf.
Typical treaty reduced rates for UK recipients:
| Income type | Treaty rate |
|---|---|
| Portfolio dividends | 15% |
| Direct investment dividends (where you own 10% or more of the paying company’s voting power) | 5% |
| Interest | 0% |
| Royalties | 0% |
Two things worth remembering:
- These are maximum treaty rates. The payer still needs a valid, correctly filled in form on file before they’ll apply them. Without it, they’ll usually withhold at the full 30% by default.
- The rate depends on the type of income. A 0% rate on royalties doesn’t automatically carry over to dividends, so check which category your payment actually falls into.
Step by Step: How to Fill In Form W-8BEN-E for UK Businesses
The form has 30 parts in total, but most UK small businesses only need to fill in a handful of them. Here’s a practical walkthrough for a straightforward UK Ltd company receiving US source payments.
Before filling in anything, confirm your company is actually receiving the income for itself and not passing it on to someone else. If you’re just collecting it on another party’s behalf, W-8BEN-E might not even be the right form.
- Line 1: Your company’s full legal name, exactly as registered with Companies House
- Line 2: Country of incorporation (United Kingdom)
- Line 3: Only fill this in if you’re disregarded for US tax purposes (rare for a standard Ltd)
- Line 4, Chapter 3 Status: Most UK limited companies select “Corporation”
- Line 5, Chapter 4 (FATCA) Status: Choose the classification that matches your entity’s actual FATCA status. Keep it consistent with any FATCA or CRS classification you’ve already given to banks. Don’t guess a different one here.
- Lines 6 to 8: Your registered UK address and mailing address (if different)
Before you get to the treaty section, work out exactly what category your US payment falls into. Services income, royalties, dividends, and interest are all treated differently, and the treaty article and rate you can claim depends on it.
This is the part that trips people up the most, and the one most often left blank by mistake.
- Confirm your company is a UK tax resident
- Cite the relevant treaty article for your income type
- Confirm you meet the “Limitation on Benefits” test. The treaty only benefits genuine UK residents with real substance, not shell arrangements
- Enter the treaty rate you’re claiming (for example, 0% for royalties, 15% for portfolio dividends)
- Must be signed by someone with authority to bind the company
- Include the date and printed name and title of the signatory
- An unsigned or improperly authorised form will be rejected outright
Some clients want a signed PDF. Others want it uploaded through an onboarding portal like Stripe or Upwork. Check before you send it. A mismatched submission format is one of the most avoidable delays.
Don’t skip the Part III treaty section if you want the reduced rate applied. Leaving it blank just means the payer defaults to 30% withholding.
Common Mistakes That Get W-8BEN-E Forms Rejected
- Using the wrong form entirely: sole traders submitting W-8BEN-E instead of W-8BEN, or LLPs submitting W-8BEN-E without checking if W-8IMY applies
- Leaving Part III blank while still expecting a treaty reduced rate
- Mismatched details, like a company name or address that doesn’t match your Companies House record
- Unauthorised or missing signature, where someone without signing authority signs it, or it’s submitted unsigned
- Wrong Chapter 3 or Chapter 4 classification, one that doesn’t match your entity’s real status or what you’ve told banks elsewhere
- Claiming treaty benefits without support, with no real beneficial ownership analysis behind the claim
- Letting the form go stale. Forms are generally treated as valid for a limited period (often cited as three calendar years), and any change in your company’s circumstances can invalidate it sooner. Always check the current IRS instructions rather than assuming an old form still holds
- Wrong submission format, like sending a signed PDF when the client’s portal needed a direct upload, or the other way around
What Happens After You Submit the Form
You don’t send Form W-8BEN-E to the IRS directly. Your US client or payer keeps it on file to support their withholding position and reporting obligations. Once it’s accepted, they apply the treaty reduced rate (where it’s claimed and supportable) to your future payments. If your company’s circumstances change (say there’s a change in ownership, structure, or tax residence) you’re expected to submit an updated form promptly rather than relying on the old one.
FAQs
Do I need a US EIN to complete a W-8BEN-E?
Usually not. Most UK limited companies can complete the form using their UK tax reference instead of getting a US Employer Identification Number. A US EIN or ITIN only becomes relevant if you’re claiming certain exemptions or have a direct US tax filing obligation. Check with an accountant if you think this applies to you.
What if I don’t have a US client yet? Should I fill one out anyway?
No. There’s no benefit to submitting the form speculatively. Fill it in once a specific US payer actually asks for it, since the form is tied to a particular payment relationship and income type.
What happens if I don’t submit this form at all?
Your US payer will generally default to withholding the full 30% instead of the reduced treaty rate, and in some cases they may not be able to pay you through their platform at all until the form is on file.
Can a sole trader use W-8BEN-E?
No. Sole traders are treated as individuals for US tax purposes, so you should use Form W-8BEN instead. This is one of the most common form selection mistakes.
Does the form need to be renewed?
Forms in the W-8 series are generally treated as valid for a limited period and should be refreshed if your company’s circumstances change. Don’t assume an old signed copy still counts. Check the current IRS instructions before relying on one, especially if it was signed several years ago.
Does submitting this form mean I now have to file US taxes?
No. Submitting Form W-8BEN-E confirms your foreign status and treaty position, but it doesn’t by itself create a US tax filing obligation. Whether you have any separate filing requirement depends on your wider circumstances.
What if my client uses a platform like Stripe, PayPal, or Upwork instead of a plain PDF form?
Many platforms build the same W-8BEN-E questions into their own onboarding process. The information you need (entity details, Chapter 3 and 4 status, treaty claim) is the same. Just follow the platform’s format rather than uploading a separate PDF unless they ask you to.
Quick Recap Checklist
- Confirm you’re the beneficial owner of the income
- Confirm the correct form for your entity type (Ltd goes to W-8BEN-E, sole trader goes to W-8BEN, LLP needs to check classification first)
- Identify your income type and the applicable treaty article
- Fill in Part I with details matching your Companies House record exactly
- Complete the Part III treaty claim, don’t leave it blank if you want the reduced rate
- Get it signed by someone with proper authority
- Submit it in the format your client actually wants
- Set a reminder to review or renew it before it goes stale
Not sure which form applies to your situation?
If your situation involves an LLP, multiple entities, or a less common income type, it’s worth having a short conversation with an accountant who knows UK US cross border tax before you submit anything. Getting the classification right the first time saves you from delayed payments later.
Talk to an AccountantDisclaimer: This article is general information only and not tax or legal advice. Tax rules, IRS Form W-8BEN requirements, and treaty provisions can change and depend on your individual circumstances. Always confirm against current IRS or HMRC guidance and speak to a qualified advisor before relying on this for a treaty claim.


